Essential Changes for Service Exporters | Biz Flow Kit
Exporters should also check the documentation and submission procedure prescribed by their respective AD bank. RBI requires Authorised Dealers to maintain documented policies and SOPs covering documents, timelines, charges and related processes.
Who must file an EDF for export of services?
The regulation does not restrict the requirement to large companies, IT companies, or independent third-party exports.
If there is a provision of services from India to a person outside India, the transaction can constitute an export for FEMA purposes.
Typical examples include:
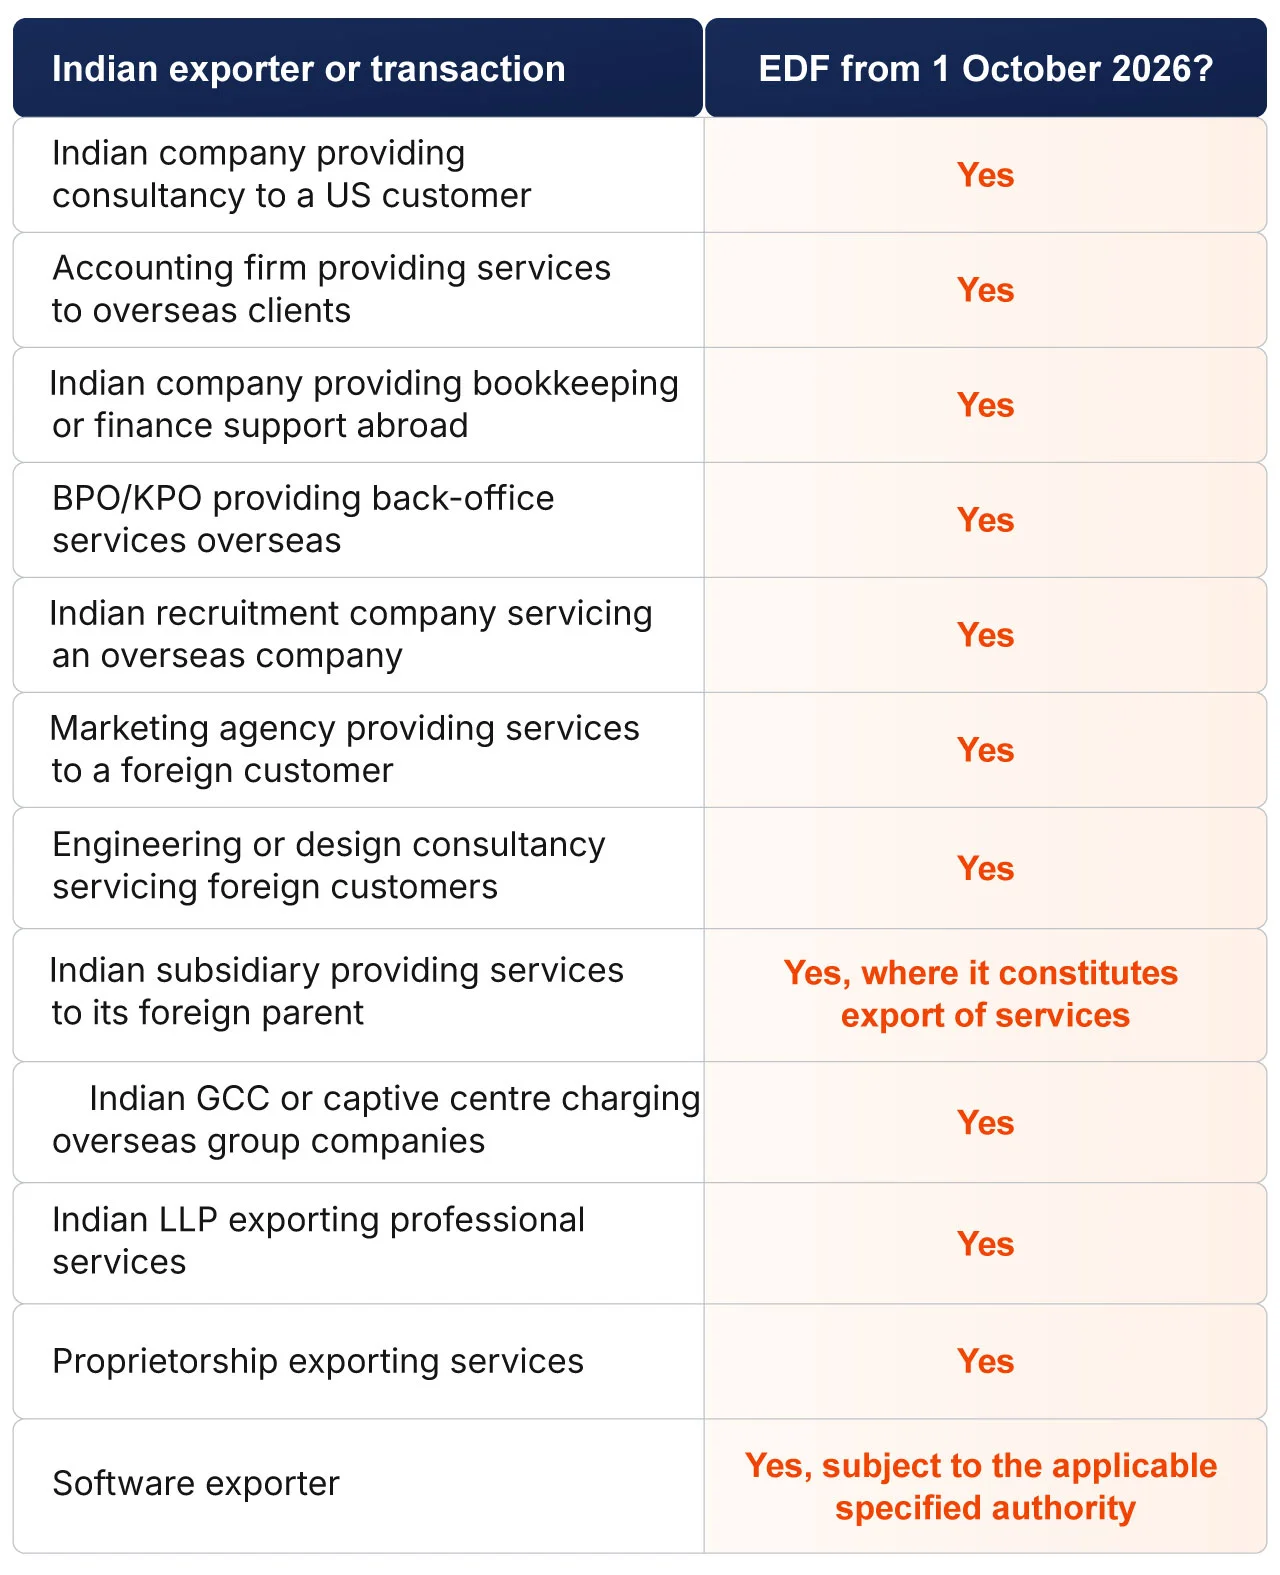
The 2026 Regulations do not provide a general exemption merely because an exporter is small, its customer is a related party, or the exporter is not registered under GST in a particular case.
Is EDF required when an Indian subsidiary invoices its foreign parent?
Yes, where the Indian subsidiary is actually providing services from India to the overseas parent.
Consider a hypothetical example.
ABC India Private Limited is a wholly owned subsidiary of ABC Inc., USA. ABC India employs staff in India and provides:
- Finance and accounting support
- Bookkeeping
- HR and recruitment support
- Management services
- Compliance coordination
- Marketing support
- Research
- Administrative services
- Customer support
- Other back-office services
ABC India raises monthly invoices on ABC Inc. under an inter-company service agreement, possibly using a cost-plus transfer-pricing model.
The transaction does not fall outside the EDF framework simply because ABC Inc. owns ABC India.
Where ABC India provides services from India to its overseas parent:
ABC India = Service exporter → ABC Inc. = Overseas recipient → EDF filing must be examined and complied with.
The 2026 Regulations do not provide a general related-party exemption from the service EDF requirement.
Businesses operating such structures should also review FEMA compliance in India and the legal framework for setting up an Indian subsidiary.
Example of monthly consolidation
Suppose ABC India raises the following invoices in October 2026:
|
Invoice |
Overseas recipient |
Nature of service |
Value |
|
INV-101 |
ABC Inc., USA |
Finance and accounting support |
USD 30,000 |
|
INV-102 |
ABC Inc., USA |
Management support |
USD 10,000 |
|
INV-103 |
XYZ Group Ltd., UK |
Business support |
GBP 8,000 |
ABC India does not necessarily need three separate EDFs.
The regulations allow one EDF to cover services exported to one or more recipients during a month. Therefore, the eligible October service exports may be consolidated into a single EDF.
What if the Indian subsidiary exports software?
Software is also covered under the 2026 service-export framework.
However, the specified authority differs depending on the type and location of the exporter.
|
Type of service |
Specified authority |
|
Non-software services from DTA |
Authorized Dealer |
|
Software from DTA |
Authorised Dealer or STPI |
|
Services or software from SEZ |
Development Commissioner of SEZ |
Businesses should first determine whether the underlying activity falls within the FEMA definition of software. A technology-enabled, support, or back-office activity should not automatically be classified as software merely because technology is involved.
Who may not need a service EDF?
The main question is whether the underlying transaction is an export of services from India.
|
Situation |
Service EDF? |
|
An Indian company provides services to another Indian company. |
Generally no service-export EDF |
|
Indian subsidiary invoices an Indian group company |
No service-export EDF merely because the ultimate parent is overseas |
|
An Indian company imports services from a foreign supplier. |
No export EDF; import requirements apply separately. |
|
A foreign customer receives services from India. |
The foreign customer does not file; the Indian exporter files. |
|
Receipt represents genuine equity or share capital. |
Not a service-export transaction. |
|
A receipt represents a genuine loan or capital transaction. |
Not a service-export EDF transaction; separate FEMA rules may apply. |
|
Dividend from overseas investment |
Not a service export. |
|
Pure reimbursement with no underlying service element |
May fall outside service EDF depending on substance |
|
Export of goods only |
Service EDF does not apply; goods-export reporting applies. |
The classification should be based on the actual substance of the transaction, not only on the description used on an invoice.
Are reimbursements received from foreign parents exempt?
Not automatically.
Calling an amount a “reimbursement of expenses” does not by itself establish that there is no service export.
If an Indian company performs functions for an overseas group entity and recovers the associated expenses, the underlying agreement, activities performed and basis of recovery should be reviewed.
EDF classification under FEMA should also be considered separately from GST, income tax, transfer pricing and accounting treatment.
Businesses dealing with related-party pricing can separately review transfer pricing at arm’s length in India.
Is there a minimum invoice value for EDF filing?
The service-export EDF provision itself does not prescribe a general minimum invoice threshold.
The 2026 Regulations separately use the ₹10 lakh threshold for certain EDPMS closure and reduction or non-realization procedures.
For example, where a service invoice is up to ₹10 lakh or its equivalent in foreign currency, an EDPMS entry may be closed on the basis of an exporter declaration regarding realisation. RBI also allows quarterly declarations for bulk closure in specified cases.
Therefore:
Invoice below ₹10 lakh ≠ automatic exemption from EDF filing.
When must a service exporter file the EDF?
Regulation 3(2) lays down the general rule that an exporter of services must furnish EDF within 30 days from the end of the month in which the service invoice is raised.
For example:
An invoice raised on 5 October 2026, 20 October 2026 or 31 October 2026 falls in the October reporting period.
The general 30-day timeline runs from the end of October, meaning the October EDF would ordinarily be submitted by 30 November 2026.
A single EDF may include all eligible October service exports.
Special provision for non-software services
The regulation additionally states that an exporter of services other than software may submit an EDF on or before the date of receipt of payment.
This is important, but it should not be read as saying that EDF filing itself is optional.
The underlying obligation uses mandatory language: an exporter of services “shall furnish” an EDF.
The provision relating to receipt of payment concerns the timing of submission for non-software services. Exporters should follow the operational SOP issued by their respective AD bank on how this option will be implemented.
The AD bank may also extend the period for submission where the exporter requests an extension, gives reasons for the delay, and the AD is satisfied with those reasons.
How will a non-software service exporter file EDF?
For a normal DTA service exporter, the process should broadly work as follows:
- Maintain invoice-wise details of all services exported during the month.
- Prepare the prescribed EDF covering the applicable export invoices.
- Where appropriate, use a single consolidated EDF for multiple invoices and multiple overseas customers for the month.
- Submit the EDF and supporting documents required under the AD bank’s SOP to the AD bank.
- The AD bank records the service EDF in EDPMS, monitors receipt of the export proceeds, and closes or updates the transaction after realization.
RBI requires an AD to enter details of a service EDF into EDPMS within five working days of receiving the EDF from the exporter.
The Regulations also require every AD to maintain a documented internal policy and SOP dealing with export/import transactions, including documents, timelines and charges, and to disclose the main features of the SOP on its website.
Therefore, there may not be one identical customer-facing filing method across every bank. An exporter may ultimately submit through the bank’s trade portal, corporate banking system or another mechanism prescribed by that AD.
The exporter should follow its own bank’s published process.
Does the exporter directly upload the EDF into EDPMS?
Normally, no.
The regulation places the responsibility on the authorized dealer to enter its customer’s service EDF details into EDPMS within five working days after receiving the EDF.
So for an ordinary DTA non-software exporter, the practical chain is:
Exporter → AD bank → EDPMS
rather than:
Exporter → direct EDPMS filing
What happens after EDF is filed?
The filing creates an export record that can be tracked through EDPMS.
The AD bank must monitor the transaction and, once the export value is realized, mark off the corresponding entry in EDPMS.
Under the new regulations, the full export value of services generally has to be realized and repatriated within 15 months from the date of invoice.
Where the export is invoiced or settled in Indian rupees, the prescribed period is 18 months, subject to the regulations and permitted settlement framework. The AD may grant an extension where it is satisfied with the reasons for delay.
Does invoicing the foreign parent in INR avoid EDF?
No.
The EDF obligation and the currency in which an export invoice is denominated are separate issues.
The new regulations themselves contemplate exports being invoiced or settled in Indian Rupees and prescribe a separate 18-month realization period for such cases.
Accordingly, an Indian subsidiary cannot assume that an intercompany service invoice falls outside EDF merely because it is denominated in INR.
Does receiving payment through PayPal, Stripe or another payment platform remove the EDF requirement?
The method through which payment is collected does not by itself determine whether the transaction is an export of services.
If the underlying transaction is a service exported from India to a person outside India, the FEMA reporting requirement must be examined independently.
Exporters using payment gateways should particularly ensure that their invoice records, bank credits, purpose codes and EDF/EDPMS entries can ultimately be reconciled.
Does having or not having an IEC determine EDF applicability?
No. These are separate compliance questions.
IEC requirements arise primarily under the foreign trade framework administered by DGFT.
The EDF requirement discussed here arises under FEMA and the RBI’s Export and Import Regulations.
Whether a particular service exporter requires an IEC should therefore be analyzed separately; the presence or absence of an IEC should not by itself be used to determine whether a service transaction has to be declared under FEMA.
Practical checklist for Indian subsidiaries billing foreign parent companies
Indian subsidiaries that regularly raise inter-company invoices should review their process before 1 October 2026.
Particular attention should be given to the service agreement, nature of services, software versus non-software classification, invoice date, foreign parent/group-company details, invoice value and currency, AD bank through which receipts are routed, monthly EDF preparation, EDPMS reconciliation and realisation of outstanding export invoices.
For cost-plus arrangements, the final invoice amount reported for FEMA purposes should be capable of reconciliation with the invoice and the underlying inter-company arrangement.
EDF compliance should also be coordinated with the company’s GST, transfer-pricing, and accounting records, although those compliances operate under separate laws.
Planning or operating an Indian subsidiary?
Businesses with an Indian subsidiary that regularly invoices a foreign parent or overseas group company should review their FEMA, banking, transfer-pricing, and related compliance processes together.
Ebizfiling can assist businesses with Indian subsidiary setup and FEMA cross-border business advisory to understand the regulatory requirements connected with international operations.
Explore Indian Subsidiary Registration or consult Ebizfiling’s Global Business Advisory experts.