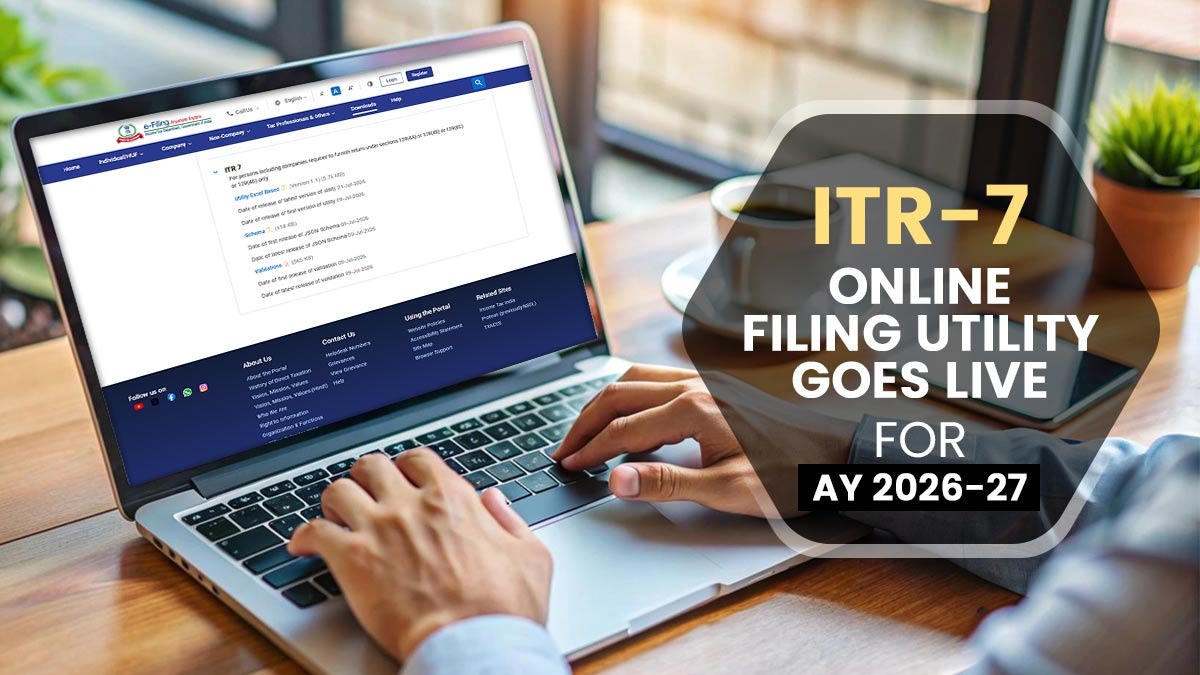
The Income Tax Department on the e-filing portal has allowed the online filing utility for ITR-7 for Assessment Year (AY) 2026-27. It authorises eligible taxpayers to file their income tax returns electronically.
It has arrived as a significant relief for trusts, charitable institutions, political parties, research associations, educational institutions, hospitals, and other entities needed to file returns using Form ITR-7.
ITR-7 is for people and entities needed to provide returns under particular norms of the income tax act that includes:
Charitable and religious trusts
Political parties
Scientific research associations
Educational institutions and universities
Hospitals and medical institutions
Other entities claiming exemptions under relevant provisions of the Income-tax Act.
With the availability of the online utility, eligible taxpayers can complete and file their returns via the income tax department’s e-filing portal.
Online Process Availability
The online utility activation shows that taxpayers are no longer required to wait for additional filing support to start the return filing procedure. Eligible entities can:
Access the e-Filing portal
Select ITR-7 for AY 2026-27
Enter income, exemption, and compliance details
Validate the information
Submit and check the return online
Before filing, tax professionals and institutions can review disclosures and supporting schedules to ensure precision and compliance.
Significance of Trusts and Exempt Entities
For companies that relish tax exemptions, timely filing of ITR-7 is important. Late filing can affect exemption claims and lead to compliance-related outcomes under the Income Tax Act.
Tax experts recommend institutions reconcile financial statements, audit reports, donation records, and exemption-related disclosures before filing the return.
Compliance Reminder
Entities needed to submit ITR-7 must check
Registration and approval details
Audit report requirements, if applicable
Exemption claim disclosures
Income and application of funds
Details of donations and grants received
Verification and e-signing requirements
Return filing ahead of time can help prevent last-minute technical issues. It also provides adequate time to correct any discrepancies determined in the filing procedure.
Closure
The decision of the income tax department to allow the online utility for ITR-7 for AY 2026-27 specifies another crucial measure in the ongoing return filing season. Eligible trusts, institutions, and exempt entities can move forward with filing their returns via the e-filing portal. It ensures compliance with the income tax provisions within the specified time.
Taxpayers who come within the ITR-7 category should analyze their records and finish the filing procedure before the deadline to prevent penalties and compliance issues.
FAQ about ITR-7 Online Utility
Q.1 What is the function of ITR-7 online utility?
The ITR-7 online utility is for eligible taxpayers, including trusts, charitable institutions, political parties, and other entities, to submit their income tax returns for Assessment Year (AY) 2026-27 electronically through the e-Filing portal.
Q.2 Who can file via ITR-7?
ITR-7 is for persons and entities mandated to file returns under the provisions of the Income-tax Act, such as charitable and religious trusts, political parties, scientific research associations, educational institutions, hospitals, and other entities claiming exemptions.
Q.3 Can I submit my ITR-7 before the deadline?
Yes, the online utility is now available. It permits eligible taxpayers to submit their returns via the e-filing portal. Early filing prevents last-minute hassles.
Q.4 What are the advantages of filing ITR-7 online?
Online filing signifies that taxpayer can access additional filing support quickly and can finish and submit their returns directly and electronically via the income tax department’s e-filing portal.
Q.5 Why is timely filing of ITR-7 crucial for exempt entities?
Organisations with tax exemptions should submit ITR-7 on time, as delays can affect exemption claims and cause compliance consequences under the Income-tax Act.
Disclaimer:- “All the information given is from credible and authentic resources and has been published after moderation. Any change in detail or information other than fact must be considered a human error. The blog we write is to provide updated information. You can raise any query on matters related to blog content. Also, note that we don’t provide any type of consultancy so we are sorry for being unable to reply to consultancy queries. Also, we do mention that our replies are solely on a practical basis and we advise you to cross verify with professional authorities for a fact check.”
Published by Arpit Kulshrestha
Arpit Kulshrestha seeks higher interests in financial services, taxation, GST, I-T, etc. Writes articles with depth knowledge and is extensive for the same. The resources provide effective articles for the products of SAG infotech which provides taxation and IT software. Writing from observations and researching makes his articles virtuous.
Contains information related to marketing campaigns of the user. These are shared with Google AdWords / Google Ads when the Google Ads and Google Analytics accounts are linked together.
90 days
__utma
ID used to identify users and sessions
2 years after last activity
__utmt
Used to monitor number of Google Analytics server requests
10 minutes
__utmb
Used to distinguish new sessions and visits. This cookie is set when the GA.js javascript library is loaded and there is no existing __utmb cookie. The cookie is updated every time data is sent to the Google Analytics server.
30 minutes after last activity
__utmc
Used only with old Urchin versions of Google Analytics and not with GA.js. Was used to distinguish between new sessions and visits at the end of a session.
End of session (browser)
__utmz
Contains information about the traffic source or campaign that directed user to the website. The cookie is set when the GA.js javascript is loaded and updated when data is sent to the Google Anaytics server
6 months after last activity
__utmv
Contains custom information set by the web developer via the _setCustomVar method in Google Analytics. This cookie is updated every time new data is sent to the Google Analytics server.
2 years after last activity
__utmx
Used to determine whether a user is included in an A / B or Multivariate test.
18 months
_ga
ID used to identify users
2 years
_gali
Used by Google Analytics to determine which links on a page are being clicked
30 seconds
_ga_
ID used to identify users
2 years
_gid
ID used to identify users for 24 hours after last activity
24 hours
_gat
Used to monitor number of Google Analytics server requests when using Google Tag Manager